Aviva plc Q3 2026 Trading Update
November 13, 2026 – (London, UK) – To read this update in full, please click here.
Amanda Blanc, Group Chief Executive Officer, said:
“Aviva is in great shape. Our performance has been excellent in the first nine months of 2026, demonstrating once again the benefits of scale across our diversified business. We continue to deliver strong, profitable growth, particularly in the capital-light areas of General Insurance and Wealth.
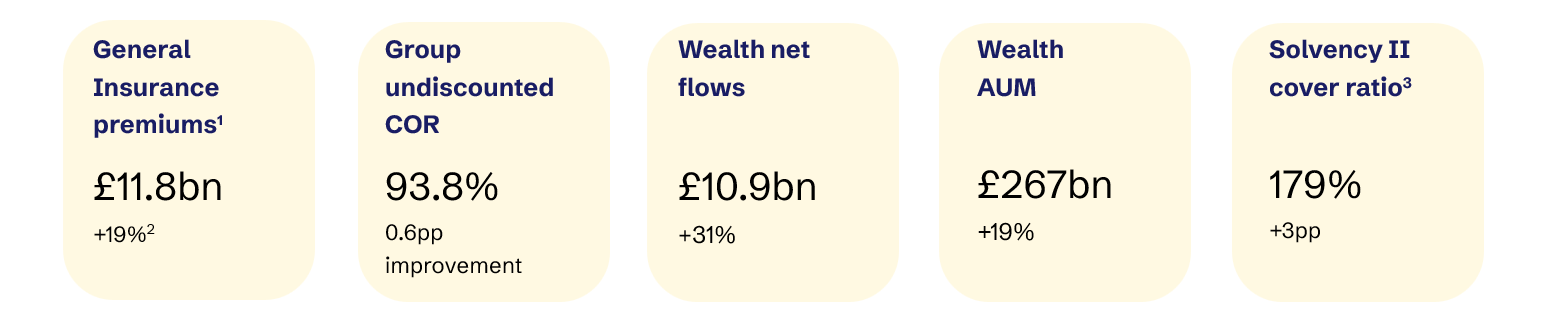
“We grew General Insurance premiums by 19% and, at the same time, improved profitability. In the UK, premiums are up 28%, boosted by our home insurance partnership with Nationwide and the great progress we are making with Direct Line. We see many opportunities to continue our profitable growth in General Insurance, including growing Direct Line motor and home policies on price comparison websites, the launch of Aviva pet insurance this year, and through our market leading businesses in Canada and Ireland. We are also continuing to deliver for our customers. Last month we started rolling out our AI virtual assistant for customers and our new multi-vehicle cover is now live, so a family with several cars can now insure them all under one policy.
“In Wealth, we are the number one UK player and have grown assets under management by 19% to £267 billion. Our strong momentum continues with flows up 31% to £10.9 billion and we now have over six million Wealth customers. We see significant opportunities for Aviva to expand further – across our Workplace, Adviser and Direct businesses – giving us confidence that we will achieve at least £280 million of operating profit in Wealth by 2027 and greater than £500 million by 2032.
“We are confident about the remainder of 2026 and expect earnings per share to grow broadly in line with our target of 11% this year. Aviva’s continued strong trading, our strengths in artificial intelligence, and our leading market position, reinforce our confidence that we will meet our three-year financial targets and grow earnings over the longer term.”
Another quarter of delivery
- General Insurance premiums up 19% to £11.8bn (9M25: £10.0bn).
- UK&I GI premiums up 27% to £8.5bn (9M25: £6.7bn) with 54% growth in personal lines, supported by the acquisition of Direct Line and continued growth in Intermediated business. Commercial lines were 5% lower as we maintained underwriting discipline to focus on profitability in current market conditions.
- Canada GI premiums up 2% in constant currency to £3.3bn (9M25: £3.3bn) with personal lines up 4% supported by pricing actions across auto and property, while commercial lines were flat as larger scheme wins in GCS have been partly offset by the competitive rating environment.
- Group undiscounted combined operating ratio (COR) improved 0.6pp to 93.8% (9M25: 94.4%) as strong rate adequacy and favourable prior year development were partly offset by elevated weather-related activity in Canada in Q3. Discounted COR of 89.8% (9M25: 90.4%).
- Wealth net flows of £10.9bn (9M25: £8.3bn) were up 31% representing 6% of opening Assets Under Management4 (‘AUM’), with strong growth in Workplace and Platform.
- Protection sales1 of £260m (9M25: £266m) were 2% lower reflecting a strong prior period in Group Protection, which included a large scheme win.
- Health in-force premiums grew 1%, while we maintained a low-90s combined operating ratio. Health sales of £81m (9M25: £118m) were 31% lower reflecting continued but slower market growth in the consumer and SME channels.
- Retirement sales of £3.5bn (9M25: £5.3bn), with Individual Annuities sales up 7% and Equity Release sales up 11%. BPA volumes were £1.9bn (9M25: £3.9bn) while year-to-date volumes, including deals where we are preferred provider, have now reached £5.8bn, ahead of the £4.6bn written across full year 2025.
- Aviva Investors delivered continued growth with total net flows of £1.5bn (9M25: £nil) and with c.65% of Workplace net flows going into Aviva Investors’ funds.
Strong solvency and liquidity positions
- Estimated Solvency II shareholder cover ratio of 179% (HY26: 176%) benefitted from total capital generation over the quarter (+8pp), partly offset by the interim dividend (-5pp).
- Total capital generation of 8pp was driven by strong operating capital generation, despite the impact of elevated CATs in Canada, 2pp of IWR management actions, and positive market movements from interest rate rises in our core markets.
- We expect the solvency ratio to be in the high-180s by the end of 2026, including >7pp from the remaining Direct Line capital synergies, subject to market movements.
- Solvency II debt leverage ratio of 30.0% (HY26: 30.8%).
- Centre liquidity at the end of October 2026 of £1.3bn (July 2026: £1.5bn).
Confident outlook
- We are already majority capital-light5 and continue to accelerate by investing in key growth areas across our diversified business. The performance in the first nine months of 2026 reflects our continued momentum across the Group and gives us confidence for the remainder of the year.
- We are on track to deliver our three-year Group targets: Operating EPS CAGR of 11% (2025-28); IFRS Return on Equity of >20% (by 2028); and Cash remittances of >£7bn (2026-28 cumulative).
- We continue to expect operating EPS growth in 2026 to be broadly in line with our 11% target rate.
- Cash remittances are weighted towards the first half in 2026 with £1.5bn, and we expect c.£0.8bn in the second half, bringing the total for 2026 to c.£2.3bn.
- We expect the solvency cover ratio to be in the high-180s by the end of the year, subject to market movements.
- In General Insurance, we continue to manage the cycle with disciplined underwriting. We are on track to meet our 2026 guidance for the UK&I GI business to achieve a COR of <94% and for the COR in Canada to be approaching 94%. In commercial lines, we expect the softer rating environment to persist in the coming months and we will continue to prioritise underwriting discipline.
- We expect to see continued momentum on the Direct Line integration and business performance improvement, with c.£130m cumulative run-rate cost synergies and the remaining >£350m capital synergies (of the >£500m total) expected to be achieved by the end of 2026.
- In Wealth, we expect continued growth momentum underpinned by our Workplace business which continues to see £1.1bn of inflows from regular member contributions each month, with the next inflows from the Mercer Master Trust anticipated in Q426. We are on track to meet our ambition for at least £280m operating profit by 2027 and greater than £500m6 operating profit by 2032.
- In our Health business, we have observed continued but slower market growth in the consumer and SME channels. We expect operating profit for 2026 to be c.£90m, and we continue to invest in the business to capture the attractive long-term growth opportunity.
- In BPA, year-to-date volumes, including deals where we are preferred provider, have now reached £5.8bn. We do not expect this number to increase materially before the end of the year. In Individual Annuities, we expect continued growth, supported by the launch of new propositions.
Footnotes
- Sales for Insurance (Protection and Health) refers to Annual Premium Equivalent (APE). Sales for Retirement (Annuities and Equity Release) refers to Present Value of New Business Premiums (PVNBP). Premiums for General insurance refer to gross written premiums (GWP). The first instance of each reference has been footnoted. However, this footnote applies to all such references in this announcement. PVNBP, APE and GWP are APMs.
- All GWP movements are quoted in constant currency unless otherwise stated. Direct Line is included in GWP for the full period of 9M26 and three months of GWP is included for 9M25.
- Solvency II shareholder cover ratio is the estimated Solvency II shareholder cover ratio at 30 September 2026.
- Calculated by annualising net flows in the period, and expressing these as a proportion of the opening AUM as at 1 January.
- Capital-light refers to Aviva’s General Insurance, Wealth, Protection and Health and Aviva Investors businesses.
- 2032 Wealth ambition assumes market returns broadly in line with our expectations.
- Rounding differences apply.